Our RMD Calculator Is Live: Features and How to Use It
By RMDCalculators.com · Published
I like tools that make the next step obvious.
Open the page. Enter your details. Understand the result.
That is what I wanted for our retirement calculator.
Because when someone wants to check a required minimum distribution, they usually have a practical question:
“How much do I need to withdraw this year?”
A useful answer should include the amount, how it was calculated, and enough context to understand it.
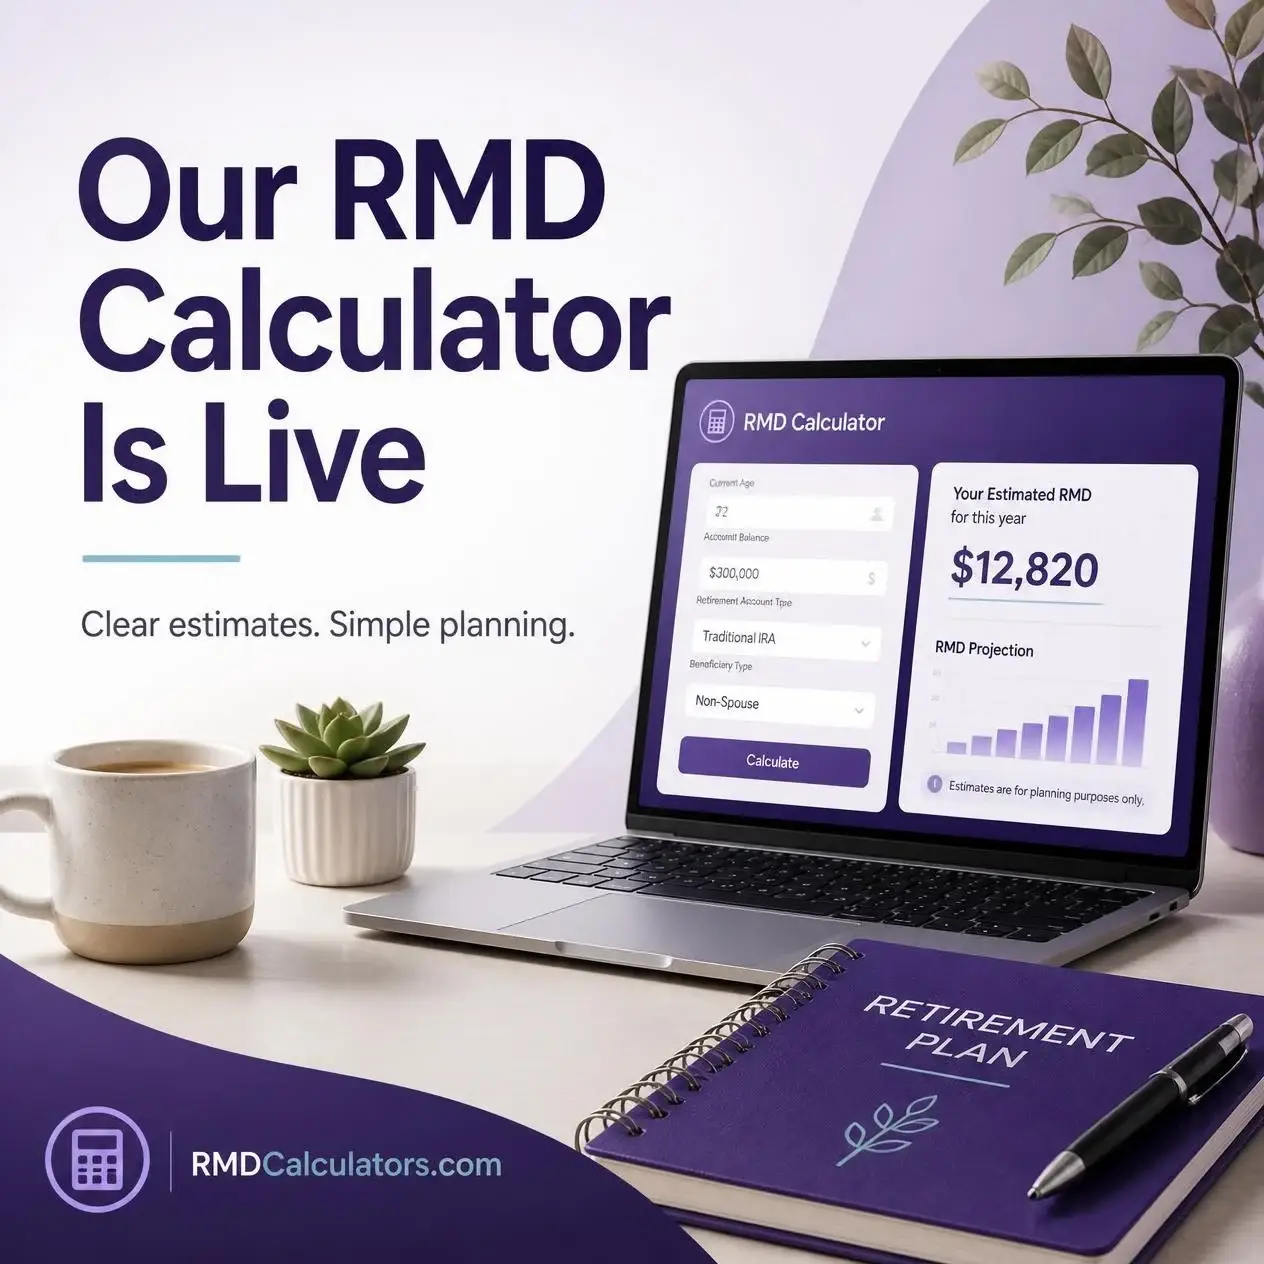
So, we have launched our RMD Calculator for 2026 at RMDCalculators.com.
The main calculator is right on the homepage. You can enter your information and get started as soon as you arrive.
Here is what we have included, and why each feature matters.
The calculator belongs on the homepage
This was an easy decision for me.
If you visit a calculator website, the calculator should be easy to find.
You can open our RMD calculator, enter your previous year-end account balance and birth year, then calculate your estimate.
There is also a growth setting for the projection feature. I will explain that in a moment.
The calculator and the explanations sit on the same page, so you can check a result and read about the method without losing your place.
What you can do with the calculator
1. Estimate your annual withdrawal for 2026
The calculator uses your birth year to determine the age you reach during 2026.
You also enter your retirement account balance from December 31, 2025.
That date matters. For a standard 2026 calculation, the starting point is the previous year-end balance. IRS guidance explains the calculation here.
Once you click Calculate my RMD, the tool displays your annual estimate for a supported account-owner situation.
The result stays close to the inputs, making it easy to change a figure and calculate again.
2. See the factor behind your result
I think a financial calculator should explain its answer.
Ours displays the IRS distribution factor used in your estimate. It also includes a formula explanation and an example you can follow.
For someone turning 73 in 2026 who uses the Uniform Lifetime Table, a $500,000 previous year-end balance produces this calculation:
$500,000 ÷ 26.5 = $18,867.92
The factor of 26.5 comes from the IRS Uniform Lifetime Table in Publication 590-B.
You can see how the numbers fit together.
3. View a monthly equivalent and withdrawal percentage
An annual figure is useful. A monthly equivalent can make it easier to picture alongside a household budget.
The calculator shows both, along with the percentage of your balance represented by the annual withdrawal.
Using the example above, you would see approximately:
- Annual estimate: $18,867.92.
- Monthly equivalent: $1,572.33.
- Withdrawal percentage: 3.77%.
The monthly figure simply divides the annual estimate by 12. It is a budgeting reference, not a requirement to take monthly payments. It also does not subtract taxes.
I like having those figures together. Each one answers a slightly different question.
4. Explore five years of projected withdrawals
This is one of my favorite features.
You can enter an assumed annual growth rate and see an illustration of five years of required withdrawals.
Each row shows the year, your age, the balance used for the calculation, and the estimated withdrawal.
Want to see what a different growth assumption would change?
Adjust the percentage and calculate again.
The model subtracts each withdrawal, then applies the assumed growth rate to the remaining balance. It does not include additional contributions.
These are planning illustrations. Actual investment returns and withdrawal timing will change the outcome.
5. Check your estimated starting year
You might be visiting before your standard age-based withdrawals begin.
The calculator accounts for that.
When your birth year puts you below its standard starting age, it shows an estimated starting year instead of an annual amount due now.
You can also read the accompanying explanation of starting ages and deadlines.
This gives you a place to begin planning, while keeping account-specific eligibility questions with your provider.
6. Compare distribution factors by age
We have included a table with selected ages, their IRS factors, withdrawal percentages, and example amounts based on a $500,000 balance.
I find a side-by-side comparison easier to understand than several separate calculations.
You can see how the factor changes with age and what that means when the example balance stays the same.
It is there on the homepage whenever you want to check it.
7. Read the explanations beside the tool
Sometimes the calculation is the easy part.
The question comes afterward.
“Which account balance should I use?”
“Does this apply to my account?”
“Where did that factor come from?”
The homepage includes worked examples, account-type explanations, starting-age and deadline guidance, and FAQs. This article also links to official IRS guidance.
You can read what you need and return to your estimate.
8. Use it on your phone, tablet, or computer
The layout adjusts for smaller screens, so you can enter your figures and review the results on the device you have available.
There is no separate app to install.
There is also a Reset button for returning to the example values, plus messages that help you correct missing or out-of-range inputs.
Small things, perhaps. But they make the tool easier to use.
9. Calculate without creating an account
The calculator is free to use.
You do not need to register or connect a retirement account.
The calculation runs in your browser using the figures you enter. It does not need your bank login to produce an estimate.
That keeps getting started straightforward.
A quick note about which situations it covers
The calculator uses the Uniform Lifetime Table for standard account-owner estimates.
Inherited accounts need separate treatment. A spouse who is your sole beneficiary and more than ten years younger can also require a different table. Workplace plans may have additional rules affecting when withdrawals begin. The IRS explains these distinctions here.
Use the result as an educational estimate, and confirm your amount and deadline with your account provider or a qualified tax professional.
Try it with your own numbers
We have put the main calculator, the result breakdown, and the supporting explanations together on the homepage.
Keep your previous year-end statement nearby.
Enter your balance and birth year.
Then take a look at your estimate.
And if there is a part of the result you would like explained more clearly, tell us.
That is useful feedback for making the next version better.