Inherited IRA RMDs and the 10-Year Rule
By RMDCalculators.com · Published
Inheriting an IRA can leave you with two different deadlines: an annual withdrawal requirement and a final date for emptying the account.
The confusing part is that the 10-year rule does not always let you leave everything untouched until year ten.
Many beneficiaries must empty an inherited IRA by December 31 of the tenth year after the owner’s death. Some must also take annual required minimum distributions during that period.
Which rules apply depends on the account, your relationship to the owner, and whether the owner died before their required beginning date.
Here is how to separate those questions and plan your next steps. Our inherited IRA RMD calculator can estimate withdrawals for supported adult beneficiaries.
What Does the 10-Year Rule Mean?
The 10-year rule generally applies to individual beneficiaries who are not eligible designated beneficiaries when an IRA owner dies after 2019.
It requires the inherited account to be fully distributed by December 31 of the tenth year following the year of death.
For example, if the owner died in 2025, the deadline is generally December 31, 2035.
The clock follows the year of death. It does not restart when you open the inherited account or transfer it to another provider.
The rule also does not mean you must withdraw exactly 10% annually. Any annual minimum is calculated under separate rules, and the remaining balance must still leave by the final deadline.
Do You Need Annual RMDs During Those Ten Years?
For an individual beneficiary subject to the standard 10-year rule, the original owner’s required beginning date is the key dividing line.
| Account and circumstances | Withdrawals during years one through nine | Final requirement |
|---|---|---|
| Traditional IRA; owner died before required beginning date | Generally no annual RMDs | Empty account by year ten |
| Traditional IRA; owner died on or after required beginning date | Annual RMDs generally required | Empty account by year ten |
| Roth IRA; beneficiary subject to 10-year rule | Generally no annual RMDs | Empty account by year ten |
This table assumes an individual designated beneficiary who does not qualify for an exception. Spouses, certain other beneficiaries, trusts, and estates need additional review.
What Is the Required Beginning Date?
The required beginning date is a legal deadline, not simply the date someone first withdrew retirement money.
For a traditional IRA owner whose applicable starting age is 73, it is generally April 1 of the following year.
Someone might voluntarily take IRA withdrawals before that date. Those payments do not automatically mean the owner died after their required beginning date.
Likewise, an owner who failed to take required withdrawals may still have reached that date.
Check the owner’s birth date and applicable rules rather than relying only on whether they were receiving regular payments. This detail can change the beneficiary’s annual withdrawal obligations. See our first RMD deadline guide and starting-age calculator for owner deadlines.
Example: Inheriting Before the Owner’s Required Beginning Date
Suppose Elena, age 40, inherits her father’s traditional IRA after he dies at 66 in 2025. Assume she is the named individual beneficiary and does not qualify for an eligible beneficiary exception.
Her father died before his required beginning date.
Elena generally has no annual RMD requirement during 2026 through 2034, but she must fully distribute the account by December 31, 2035.
She can withdraw earlier if she chooses.
Waiting until the final year may produce a large taxable withdrawal. Comparing smaller distributions across several years can help her understand the tax implications before deciding on a schedule.
Example: Inheriting After the Required Beginning Date
Now suppose Elena’s father instead died at 80 in 2025, after his required beginning date.
Elena generally must take beneficiary RMDs beginning in 2026 and continuing through 2034 while money remains. She must also empty the remaining account by December 31, 2035.
Taking each annual minimum does not remove the final withdrawal requirement.
If her father had not completed his own 2025 RMD, the unfinished amount requires separate attention. His final RMD and Elena’s beneficiary distributions are different obligations.
Ask the provider to identify both rather than assuming one withdrawal automatically settles everything.
Who Qualifies for an Exception?
Eligible designated beneficiaries generally include:
- The deceased owner’s surviving spouse.
- The deceased owner’s child who is under age 21.
- An individual meeting the applicable disability definition.
- An individual meeting the applicable chronic illness definition.
- An individual no more than ten years younger than the owner.
These beneficiaries may qualify for life expectancy distributions instead of the standard 10-year schedule, subject to applicable rules.
The minor-child exception applies to the owner’s child, not every young relative. When that child reaches 21, a 10-year completion period generally begins.
Surviving spouses have additional choices, including potentially treating the IRA as their own. Trusts and estates have separate rules; do not assume this exception list resolves their treatment.
What Changed for Annual RMDs Starting in 2025?
The IRS provided temporary relief for certain missed beneficiary RMDs during 2021 through 2024 while clarifying the rules.
That relief was limited. It did not eliminate every inherited-account requirement or restart the 10-year period.
Final regulations generally apply beginning in 2025, including annual distributions for affected beneficiaries inheriting after the owner’s required beginning date.
For example, an account inherited following a 2021 death generally remains subject to a December 31, 2031, completion deadline. The relief years do not move that deadline to 2035.
If an applicable 2025 distribution was missed, review correction options promptly rather than assuming earlier relief continues.
How Are Beneficiary RMDs Calculated?
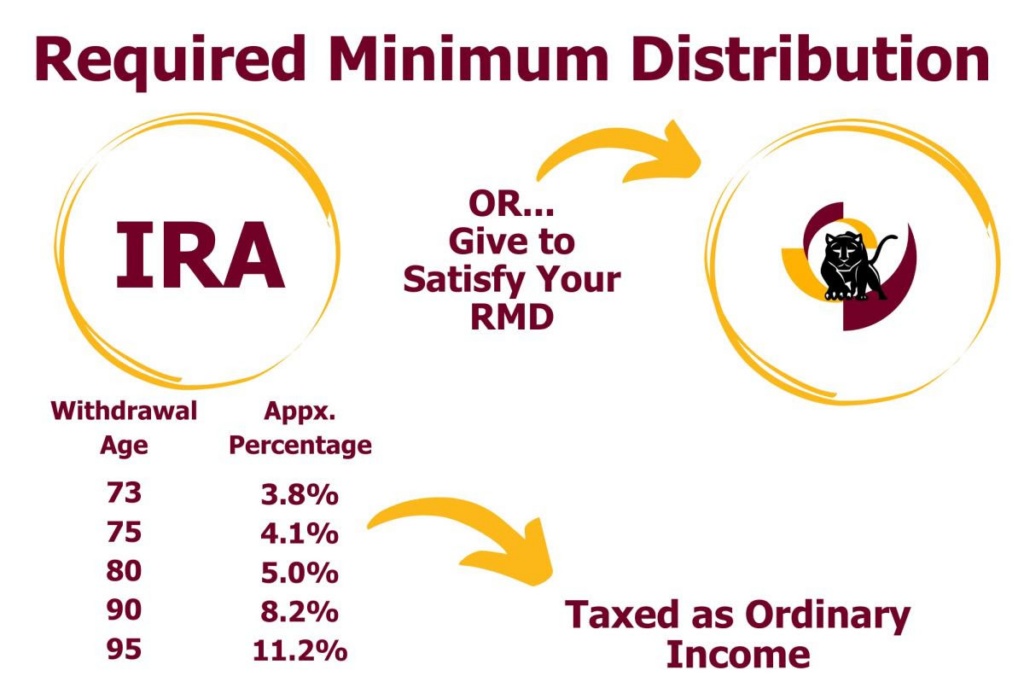
When annual beneficiary distributions are required, the calculation generally divides the previous December 31 balance by the applicable life expectancy factor.
Beneficiary calculations often use the IRS Single Life Expectancy Table, with adjustments depending on the beneficiary and inheritance history.
Do not automatically use the Uniform Lifetime Table factor for your own age. That table generally serves original owners. Our IRS distribution tables distinguish the available tables.
Ask your provider to confirm the starting factor, how it changes annually, and the deadline for complete distribution. An inherited IRA calculator is useful only when it supports your circumstances and receives accurate information.
Are Inherited IRA Withdrawals Taxable?
Traditional inherited IRA withdrawals are generally taxable, except for any applicable nontaxable basis. Beneficiary distributions generally avoid the 10% early-distribution tax, even when the beneficiary is younger than 59½.
Inherited Roth IRA distributions are generally tax-free when the Roth qualification requirements are met. Earnings can require additional attention if the five-year requirement has not been satisfied.
A Roth account can therefore have a mandatory withdrawal deadline even when distributions are tax-free.
Tax treatment and withdrawal timing are separate questions. Review both before deciding how much to take each year. The tax withholding calculator estimates net payments, not your final tax bill.
What Should You Check Each Year?
Confirm any annual RMD due by December 31 and update the amount remaining in the account. Record distributions already completed and keep the final year visible in your plan. If a required withdrawal is missed, contact the provider promptly and review correction requirements, including potential Form 5329 reporting, with a tax professional.
Conclusion
The inherited IRA 10-year rule sets a final deadline, but it may also come with annual RMDs.
Confirm the owner’s death year, required beginning date, account type, and your beneficiary classification. Then track annual withdrawals and the final distribution deadline separately. Getting those details right helps you avoid missed requirements and make more informed decisions about when to receive the money.
Sources: IRS Publication 590-B and required minimum distributions for IRA beneficiaries. Educational information only, not tax advice.